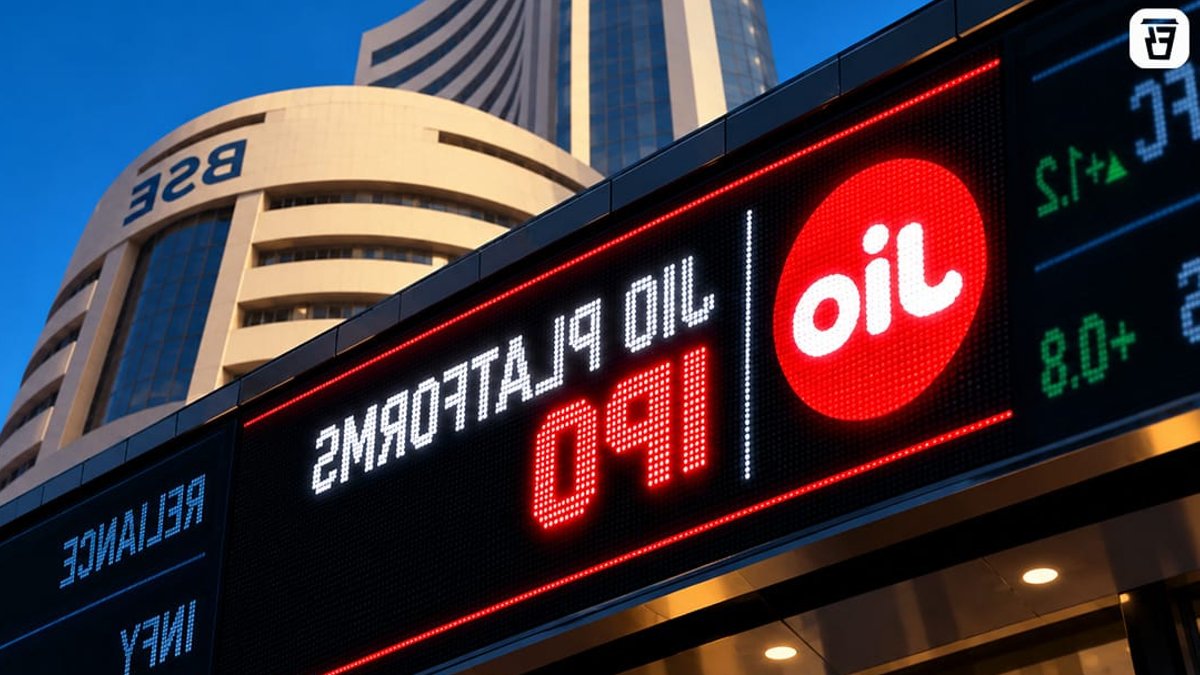
The Jio Platforms IPO is set to open for subscription on October 21st and close on October 23rd, 2026. Jio Platforms is a tech and connectivity business that generates most of its revenue through its subsidiary, Reliance Jio Infocomm, India’s largest mobile network operator. The company is going public primarily to repay some of its debt, with the IPO being entirely a fresh issue of shares worth ₹30,200 crore.
Before investing in the IPO, it’s essential to consider a few risks and factors. One key aspect is Jio’s dependence on a single distribution channel, Reliance Retail, which is its sister concern and the only distributor for prepaid plans. This dependence could be risky if the agreement between Jio and Reliance Retail changes or falls through, as Jio may need to find another distributor and establish a network of distributors across India.
Jio’s Revenue Recognition
Jio sells recharge vouchers in bulk to Reliance Retail, which pays Jio an advance. This advance is recorded as an advance rather than immediate revenue. In FY26, this advance was about ₹1.13 lakh crore. Jio then recognises the revenue over time as Reliance Retail sells the vouchers and customers use up their recharges.
The terms of the agreement between Jio and Reliance Retail could change, potentially affecting Jio’s revenue. If the terms shift in Reliance Retail’s favour, Jio could earn less from the arrangement, even if the wider Reliance group doesn’t take a significant hit. However, the current arrangement also has a positive side, as Jio doesn’t have to wait long for its money due to Reliance Retail’s upfront payment.
Cash Position and Network Spending
Jio’s cash position remains strong, with a useful metric being EBITDA minus capex. Between FY24 and FY26, Jio spent about ₹1.32 lakh crore on its network, but its annual spending has been falling. In FY26, the difference between EBITDA and capex stood at ₹42,071 crore, with Jio overtaking Airtel’s India business on this metric for the first time in Q1FY27.
Related Post: Jio Platforms Launches $3.8B IPO, India’s Biggest Listing
Despite the growth in EBITDA minus capex, Jio’s profits haven’t increased at the same pace. While EBITDA minus capex grew 111% over the past year, profits rose by just 15%. This is partly due to timing, as interest on loans funding the network can be added to the asset’s cost during construction, but starts showing up as an expense once the network becomes operational.
Jio’s finance costs jumped 76% to ₹8,653 crore in FY26, and depreciation also rose 13% as newer equipment began to be written off. Additionally, EBITDA minus capex isn’t entirely free cash, as taxes, future spectrum purchases, and AI investments could take a bite out of it. As Jio’s valuation is around 34 times earnings, it’s essential to consider the enterprise value to EBITDA metric, which can provide a more accurate comparison of its core operating earnings.
In terms of valuation, Jio trades at about 12 times EBITDA based on FY28’s expected earnings, slightly higher than Airtel’s 10. However, Airtel has higher EBITDA margins and faster profit growth, which may impact Jio’s valuation. The valuation might reflect less what Jio is today and more what investors believe it could become in the future.
The company’s profit growth has been slower than its growth in EBITDA minus capex, which may be a concern for investors. The ₹30,200 crore IPO is expected to help Jio repay some of its debt and invest in its network, which could lead to further growth and expansion.


Leave a Reply